Vermont Health Connect: 2027 premiums are up and the deadline is earlier
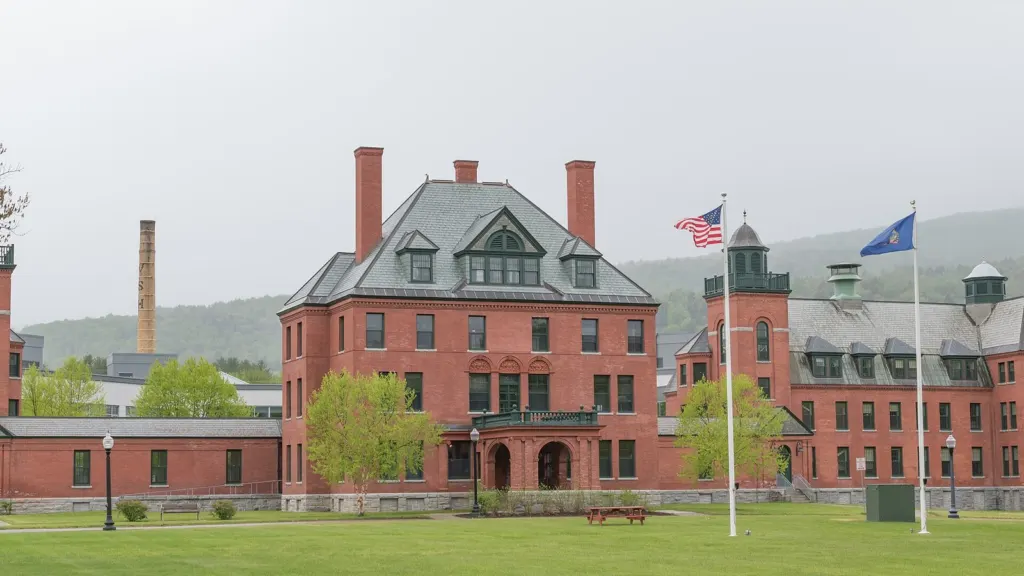
The Waterbury State Office Complex. Photo: Ɱ, CC BY-SA 4.0, via Wikimedia Commons.
Vermonters who buy their own health insurance have about five weeks to pick a 2027 plan if they want coverage to start on Jan. 1, and many will be looking at bigger bills than last year.
Open enrollment on Vermont Health Connect began Nov. 1. The deadline for Jan. 1 coverage is Dec. 15, a month earlier than the state allowed last year. People who choose a plan by Dec. 28 can still get coverage, but it won’t start until Feb. 1, according to the Department of Vermont Health Access.
Here is what has changed and what to check before you sign up.
Premiums are up again
Vermont’s individual market has two insurers, Blue Cross Blue Shield of Vermont and MVP Health Care, and both raised prices. The Gold plan for a single adult from Blue Cross now lists at about $1,391 a month before subsidies, up from $1,219 in 2025, an increase of about 14% over two years, WCAX reported. MVP’s version of the same plan is about $1,188 a month, up nearly 4% from $1,145.
Those are sticker prices. Most people who enroll through Vermont Health Connect qualify for financial help that brings the monthly cost down, sometimes by hundreds or thousands of dollars, depending on age, income and household size. “Even if you don’t know if you are, we’re encouraging everyone to go on to the plan comparison tool,” Alex McCracken of DVHA told WCAX.
The subsidy cliff is back
The bigger change happened at the end of 2025, when Congress let the enhanced federal premium tax credits expire. Those credits had capped what middle-income buyers paid for a benchmark plan. Without them, single people earning more than about $63,000 a year lost most or all of their help.
The state says about 28,500 people are enrolled in marketplace plans for 2026, a drop it blames on the expired subsidies. Mike Fisher, Vermont’s chief health care advocate, said the people who left were disproportionately those above the income limits, and that when healthier customers drop out, the people who stay cost more to insure, which pushes premiums up further.
Fisher also pointed to the underlying cost of care in Vermont. “The costs of getting care here in Vermont are a major, major factor in why our premiums are so high,” he said.
Bronze plans and the deductible trap
One response to high premiums is to drop down a tier. Fisher estimates about twice as many Vermonters picked a Bronze plan last year, which has a lower monthly premium but a much higher deductible. That can work for someone who rarely sees a doctor. It can backfire for anyone who ends up needing care and can’t cover the out-of-pocket costs. “They have health insurance, and they can’t afford to get the care they need,” Fisher said.
A few practical points for this year’s shopping:
- Run your numbers in the state’s plan comparison tool even if you didn’t qualify for help last year. Income, household size and age all change the result.
- Look at the deductible and out-of-pocket maximum, not just the premium.
- Check whether your doctors and the hospital you’d use are in network.
- If you need help, call early. Fisher warned that helplines get busy and wait times grow as Dec. 15 gets closer.
The state also notes changes to benefits this year for certain noncitizens and immigrants, so households in that situation should check eligibility before renewing.
Free help is available through Vermont Health Connect and through the Office of the Health Care Advocate, which runs a helpline for consumers with questions about coverage and bills.
Add Vermont Daily News as a preferred source on Google (opens in a new tab)